When the invoice is not enough to classify
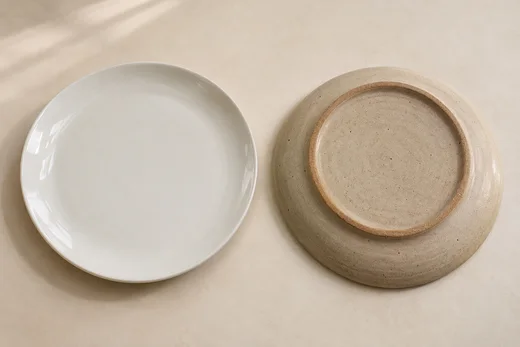
An invoice line names a product, not always the facts the tariff classifies on. A ceramic plate is 6911 if porcelain, 6912 if not.
By Lucas Duys. Published 2026-09-26, updated 2026-11-09.
An invoice line may name the goods without giving enough facts to classify them. For ceramic tableware, porcelain belongs under 6911; other ceramics belong under 6912 [1]. “Ceramic dinner plate, 27 cm” does not settle that choice. Ask the supplier for the material and intended use, which can both matter for classification [7]. Keep the answer with the invoice line.
One plate, five possible codes
These are the 2026 codes for ceramic tableware and kitchenware [1]:
| CN code | Tableware and kitchenware | Conventional duty |
|---|---|---|
| 6911 10 00 | Of porcelain or china | 12% |
| 6912 00 21 | Of common pottery | 5% |
| 6912 00 23 | Stoneware | 5.5% |
| 6912 00 25 | Earthenware or fine pottery | 9% |
| 6912 00 29 | Other | 7% |
All five lines, with their full descriptions, are in the free HS code finder. The chapter itself has a condition too: Chapter 69 applies only to ceramic products which have been fired after shaping [1]. And if the plate is not tableware at all but a decorative wall plate, it may belong in heading 6913, statuettes and other ornamental ceramic articles, where porcelain is 6% [1]. Material, use and presentation each move the code, and the invoice line settles none of them.
What the tariff asks that invoices skip
The General Rules for the Interpretation of the Combined Nomenclature make the terms of the headings and the section and chapter notes decisive [1]. The rules then deal with the cases an invoice blurs: a reference to a material covers goods made wholly or partly of it, goods of more than one material are classified by rule 3, and goods put up in sets for retail sale that rule 3(a) cannot classify are classified by the material or component that gives them their essential character, in so far as that criterion applies [1].
The declaration asks for the same precision. For a declaration for release for free circulation, the description of goods is "the normal trade description", in "terms sufficiently precise to enable immediate and unambiguous identification and classification of the goods" [2]. German customs asks declarants to supplement a description that falls short with the kind of material, the kind of processing and the intended use [3].
The origin matters as well: TARIC holds the measures attached to the tariff, from tariff preferences to anti-dumping and countervailing duties [4]. The declaration asks for the country of origin, unless a preference is claimed and the preferential origin is the same country, in which case the country of preferential origin is given [2].
Questions only the supplier can answer
A good question names the line, asks one thing, and can be answered from the product specification. For the plate:
- Material. Is the plate porcelain or china, or another ceramic? If another, is it common pottery, stoneware, or earthenware or fine pottery?
- Use. Is it made to serve food, or to be displayed as decoration?
- Presentation. Is it sold on its own, or as part of a set for retail sale, and if so, what else is in the set?
- Origin. In which country was it made, and, if a preferential rate is to be claimed, can the supplier provide the proof of origin?
The same shape works for other goods. A garment needs its fibre composition, a machine part its function in the machine, a chemical its composition and CAS number, which German customs recommends giving for chemicals [3].
Some questions belong to the buyer, not the supplier. Whether buyer and seller are related, and whether royalties are paid as a condition of sale, are questions about the value of the goods [5].
Keep the answer with the case
The person who lodges a declaration is responsible for the accuracy and completeness of its information and for the documents supporting it, and so is a customs representative who lodges it [5]. Supporting documents have to be in the declarant's possession when the declaration is lodged [5]. When customs ask for them while the goods wait, the guide on a shipment held at customs covers what to send. A supplier's written answer on the material is the kind of evidence worth keeping next to the invoice line it explains. The same goes for a code proposed by software: the guide on AI customs classification sets out what a proposal has to show before it can be checked.
When the answer is still not enough
Some goods stay uncertain after the supplier has answered. Before asking for a binding decision, anyone can contact the customs authority for general, non-binding information on the classification of goods; only a Binding Tariff Information decision is binding [6]. How to use existing decisions, and when to apply for one, is in the guide on binding tariff information.
Athren prepares the case from the shipment email and turns an unclear line into one question, ready to ask; your declarant checks what is open and files it. Athren files nothing.
Sources
- 1Implementing Regulation (EU) 2025/1926, the Combined Nomenclature for 2026, Official Journal of the European Union, 2025-10-31. Read 2026-09-26.
- 2Delegated Regulation (EU) 2021/234, Annex B: common data requirements, column H1, Official Journal of the European Union, 2021-02-23. Read 2026-09-26.
- 3Merkblatt zu Zollanmeldungen, summarischen Anmeldungen und Wiederausfuhrmitteilungen, Ausgabe 2026, Generalzolldirektion, 2025-12-08. Read 2026-09-26.
- 4EU Customs Tariff (TARIC), European Commission, Taxation and Customs Union. Read 2026-09-26.
- 5Regulation (EU) No 952/2013 laying down the Union Customs Code, Articles 15, 70, 71 and 163, Official Journal of the European Union, 2013-10-10. Read 2026-09-26.
- 6European Binding Tariff Information (EBTI), European Commission, Taxation and Customs Union. Read 2026-09-26.
- 7Informationen zur Codenummer, Zoll (German customs). Read 2026-09-26.
See Athren suggest your product’s code.
Athren suggests codes when the shipment facts are clear. It drafts questions for missing facts. Your declarant reviews the result.